A processor deposit can match the bank by amount while still carrying the wrong accounting treatment. The settlement may include a refund, a fee, or activity that belongs to another period. A rule that clears the deposit because two numbers agree has automated the match, not the reconciliation.
That distinction matters. The biggest failure in reconciliation automation is not too little AI. It is automating matches before defining which items should never clear without judgment. When the rules optimize for match rate alone, the queue gets shorter, but the reviewer loses the differences that deserved attention.
Good reconciliation automation rules do something more specific. They separate repeatable matches from judgment-heavy exceptions, define which source evidence must be present, and show the reviewer why an item cleared or did not. The goal is not to remove review. It is to stop asking accountants to recheck routine work while making meaningful exceptions easier to investigate and approve.
Why a match is not the same as a reconciliation
A bank line is one representation of an event. A processor report, donor platform export, or custodian statement may describe the same event with different dates, identifiers, fees, and dimensions. Matching two fields cannot establish that every relevant source is present or that the result maps correctly to the GL.
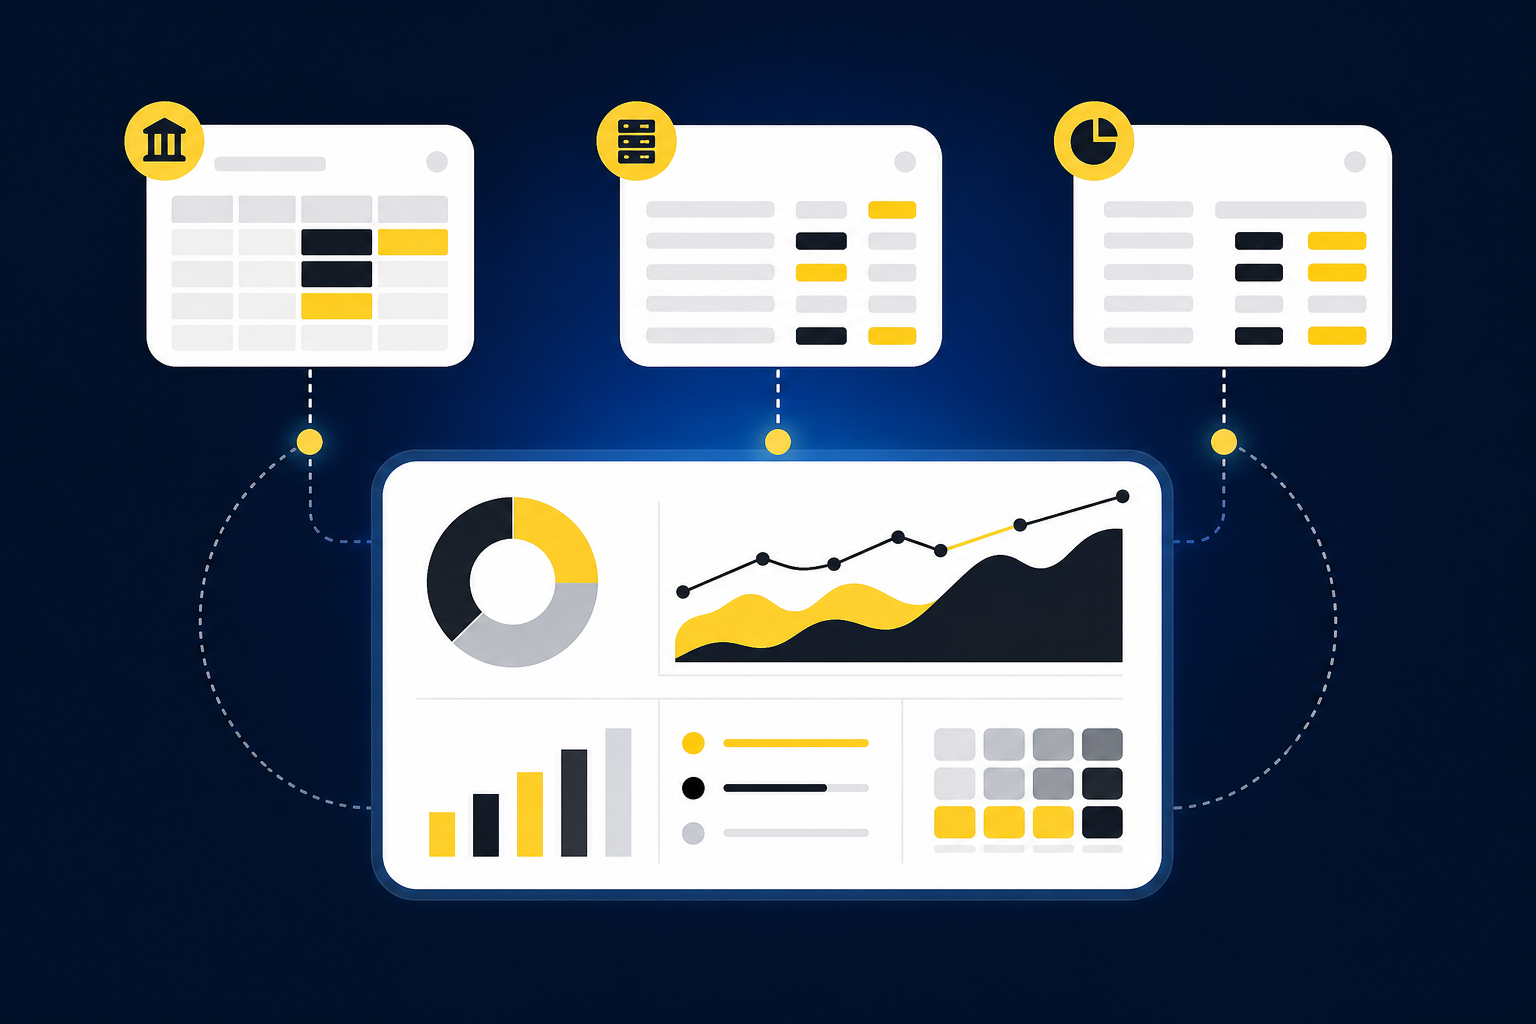
Consider a nonprofit deposit. The bank shows the net amount. The processor report carries gross donations, processing fees, refunds, and payout timing. The donor platform may carry the fund, campaign, or restriction detail the accounting team needs. A match between the bank and processor can be mathematically correct while leaving the dimensional coding incomplete.
A safe auto-match therefore needs more than agreement on amount. The expected sources must be present. The activity must fit a defined relationship across those sources. Known timing differences or fees must follow an approved rule, and the accounting treatment must remain consistent with the team’s process. When one of those conditions fails, the item belongs with a reviewer.
The rule should also explain itself. A reviewer needs to see which records were matched, which tolerance applied, what difference remained, and which source supported the treatment. Truewind prepares that source-linked review surface rather than asking the accountant to accept a clean result without its support. You can See Truewind in action to inspect how source files, matching logic, and exceptions come together in one reconciliation workflow.
Start with expected evidence, not matching logic
Before writing a match rule, define the evidence the reconciliation expects. That starts with the source set: bank activity, processor reports, donor exports, custodian statements, ERP balances, prior workpapers, or another recurring input. Each source has a role, and the rule should name it.
The next question is completeness. If a monthly custodian statement is expected but never arrives, there may be nothing for a transaction-level anomaly rule to flag. The same problem appears when a processor payout file is missing or an operational export stops before period-end. Missing evidence deserves its own workflow because an absent event is different from an unusual event contained in a file.
A completeness rule should answer practical questions:
- Which source is expected for each entity, account, or reconciliation?
- What period should the source cover?
- Which identifiers connect it to the other records?
- What happens when the file is missing, partial, or duplicated?
- Who owns the follow-up and final disposition?
Only after those conditions are defined should the workflow attempt a match. That order prevents a present bank line from standing in for evidence that never arrived.
Separate safe matches from accounting exceptions
Safe matches are recurring relationships with stable evidence and explicit treatment. A processor payout may connect to a known settlement report and bank deposit, with fees allocated according to an approved rule. A recurring transfer may connect across accounts when the entities, dates, amounts, and classifications all agree with the defined process.
Judgment-heavy items look different. Mixed personal and business activity requires a decision. A classification that conflicts with prior treatment requires review. An unexpected balance change may need investigation even when the arithmetic works. Those are not failures of automation. They are the reason the exception queue exists.
Reconciliation automation rules should preserve that boundary. The system can prepare what follows the known process, but it should not expand a rule simply because a new item resembles an old one. The accountant still owns novel treatment, policy changes, and approval.
Give every tolerance a named reason
Tolerances reduce noise when they account for a known difference. They mask discrepancies when they exist only to make more items clear.
A date tolerance may be appropriate when processor settlement timing regularly crosses a defined period boundary. An amount tolerance may account for a documented fee treatment or another approved difference. In both cases, the rule needs a stated cause, a boundary, and visible support. “Close enough” is not an accounting policy.
Materiality also does not make unexplained differences disappear. A small recurring variance may expose a mapping problem, a fee that is being coded inconsistently, or a source that is not being reconciled at the right level. The reviewer should be able to see the cumulative pattern rather than receiving isolated items with no history.
Route exceptions by cause, not into one unmatched queue
An unmatched queue tells the reviewer that something failed. It does not tell them what kind of work comes next. Missing source files, timing differences, classification conflicts, and unreconciled amounts require different evidence and different decisions.
Cause-based queues make that distinction visible. A missing statement should go to the person responsible for obtaining the source. A known timing difference should carry the related transactions and cutoff rule. A dimensional conflict should show the prior coding, current proposal, and source context needed to confirm the right fund, department, or entity.
The reviewer should not have to reconstruct the match before making a decision. Each exception should show:
- The source records involved
- The rule that ran
- The unresolved difference
- The current and prior accounting treatment
- The preparer or system action already taken
- The reviewer’s available actions
That information belongs in the workpaper. When source, calculation, treatment, exceptions, and sign-off remain together, another reviewer can trace the decision and re-perform the important steps. Email threads and spreadsheet comments do not provide the same durable review surface.
Truewind’s human-in-the-loop workflow presents prepared reconciliations beside their source links and exceptions. Accountants can confirm, adjust, or return an item to preparation, and nothing moves downstream without sign-off. To examine that reviewer handoff against your own reconciliation process, Book a Truewind demo and bring a recurring workflow with known source files and a prior approved result.
Keep rule changes under accountant control
Rules should become more consistent through review, not broader without it. Prior workpapers, confirmed classifications, allocation choices, and reviewer corrections provide useful operating context because they show how the team has handled the work before. They do not authorize the system to invent a new policy.
A controlled rule change records what changed, why it changed, when it applies, and who approved it. The next reviewer can then distinguish a deliberate change from an unexplained difference. That history matters when a treatment varies by entity, a processor changes its report, or a previously routine item becomes an exception.
Historical treatment is especially useful for recurring workflows. Truewind captures confirmed treatment and reviewer corrections against the workflow, then uses that context when preparing later periods. Reviewers can inspect the current output and the decisions that shaped it. Novel items still return to the accountant.
Measure whether the rules improve control
A rising auto-match rate does not prove that reconciliation is getting better. The rate can increase because the rules are accurate, or because the tolerances have become too broad. You need measures that show what happened after the match.
Start with reversals and reviewer corrections. If cleared items are repeatedly reopened, reclassified, or moved to another period, the rule is producing work that looks finished before it is ready. Track those corrections by rule and reason so the team can tighten the specific logic instead of adding another review pass across the entire population.
Exception volume also needs context. A lower count may mean the workflow is handling recurring items correctly. It may also mean a completeness check stopped running. Pair the count with missing-source events, unresolved balances, exception age, and the value of items still awaiting judgment.
Useful measures include:
- Auto-matched items later changed by a reviewer
- Exceptions grouped by cause and source
- Missing expected files or events
- Unresolved differences carried into the next period
- Time exceptions remain open
- Rule changes and the corrections that prompted them
None of these requires a universal benchmark. The relevant comparison is the workflow against its own approved history. A rule set is improving when routine preparation stays consistent, exceptions become more specific, and reviewers can understand why the result changed.
A narrow workflow also produces a cleaner measurement than a broad automation launch. In one customer conversation, an accounting firm reported reducing credit-card transaction categorization time by approximately 75% after applying automation to that recurring task. That result is not a reconciliation benchmark. It shows why teams should measure a bounded process with a known starting point rather than attach one outcome to the entire close.
How Truewind applies reconciliation rules upstream of the GL
Truewind starts with the source files the accounting team already receives. Bank activity, processor and donor exports, custodian statements, prior workpapers, and ERP balances are structured into a recurring workflow. The platform then applies the team’s historical treatment to prepare coding, schedules, reconciliations, and any required journal-entry draft.
Multi-source reconciliation aligns systems that describe the same activity differently. It can account for fees, refunds, and timing differences when the team’s rules define how those items should be treated. Unreconciled items are not forced to agree. They are surfaced with source context for reviewer judgment.
The workpaper carries the result. Each prepared item stays connected to its supporting source, the reviewer decisions applied, and any exception that remains. Reviewer decisions are captured in the workflow so the next period begins with the last confirmed process rather than a generic template.
Sage Intacct and QuickBooks Online remain the systems of record. Once the accountant has reviewed and approved the output, Truewind can push structured output to the connected ERP with coding, dimensions, and source references preserved. It does not post without reviewer confirmation, resolve exceptions autonomously, or replace the ledger.
That boundary is intentional. Teams looking for unsupervised posting are solving a different problem. Reconciliation rules work when the accountant owns their design, reviews what falls outside them, and approves the prepared result before anything reaches the GL.
A product walkthrough can show the specific handoff from multi-source preparation to accountant approval. Get a Truewind demo to inspect how that handoff would fit a reconciliation your team already performs.
Start with one workflow the reviewer already understands
Choose a reconciliation that recurs, has known source files, and ends in a workpaper the reviewer already accepts. Bring the prior-period inputs, the approved output, the relevant mappings, and the exceptions the team handled manually. The first test should reproduce a known result before it attempts to automate a broader part of the close.
Compare the prepared output line by line. Separate differences caused by missing evidence from differences caused by matching logic, classification, timing, or dimensional treatment. Promote a rule only when the source relationship is clear and the reviewer can explain why the match is safe.
Keep the judgment boundary visible as the workflow expands. Missing statements should remain missing-statement exceptions. Unexpected balance changes should remain in front of the accountant. New accounting treatments should not enter the rule set without review.
The useful outcome is not a queue with nothing in it. It is a reconciliation rule set that removes routine rechecking while making exceptions clearer, faster to investigate, and easier for the accountant to approve.
Frequently Asked Questions
How do I set up reconciliation automation rules?
Start by defining the expected evidence for your reconciliation. Identify the source files you typically use, like bank statements or processor reports. Next, establish completeness rules to ensure all necessary documents are present for each transaction. Finally, create match rules that specify how to handle recurring relationships and judgment-heavy exceptions. This way, you can automate routine matches while ensuring that exceptions are flagged for review.
What if a source file is missing during reconciliation?
If a source file is missing, it’s crucial to have a specific workflow for handling that scenario. First, identify which file is missing and why it’s important for the reconciliation. Then, route the issue to the responsible person for follow-up. Make sure to document the missing file in your records so that it can be addressed in future reconciliations. This helps maintain clarity and accountability within your team.
Can I automate the review process for reconciliations?
While you can automate many aspects of reconciliation preparation, the review process must remain human-led. Truewind helps by preparing workpapers and surfacing exceptions, but it does not replace the reviewer’s judgment. Ensure that your team is involved in reviewing the prepared outputs, as they will need to confirm the accuracy and appropriateness of the reconciliations before anything is posted to the general ledger.
When should I escalate reconciliation exceptions?
You should escalate exceptions when they involve judgment-heavy items, such as mixed personal and business activity or unexpected balance changes. These situations require a thorough review to determine the correct treatment. Make sure to document the reason for escalation and provide all relevant source records to assist the reviewer in making an informed decision.
Turn this into a close-ready workpaper
Start with sample files or upload your own statements to see how Truewind prepares review-ready workpapers and journal entries.