A donor export can be complete, the bank deposit can be correct, and the restricted-fund schedule can still fail review because the records do not carry the same context. The ledger may hold the final entry, but it does not remove the work required to reconcile funds, grants, processor fees, timing differences, and restrictions before posting. That is the real decision behind nonprofit accounting software. You are choosing a system of record, but you are also choosing how the work around it will get done.
TL;DR: Fit depends on complexity. QuickBooks Online may remain a reasonable choice when the current configuration already produces accepted reporting and the harder problem sits upstream of the ledger. Sage Intacct belongs in a deeper evaluation when dimensions, structured review, and nonprofit accounting workflows are central requirements. NetSuite belongs in the evaluation when entity structure, consolidation, and the broader operating model drive the ERP decision. None should win on category reputation alone; each needs to prove the required workflow in your configuration.
Start with the accounting model, not the software list
Nonprofit accounting requirements compound. A contribution may need fund, restriction, grant, program, department, and campaign context before the entry is useful to a reviewer. A deposit may combine donor activity from several sources, processor fees, refunds, and timing differences. The software decision has to preserve that context from source through reporting, not merely record the bank transaction.
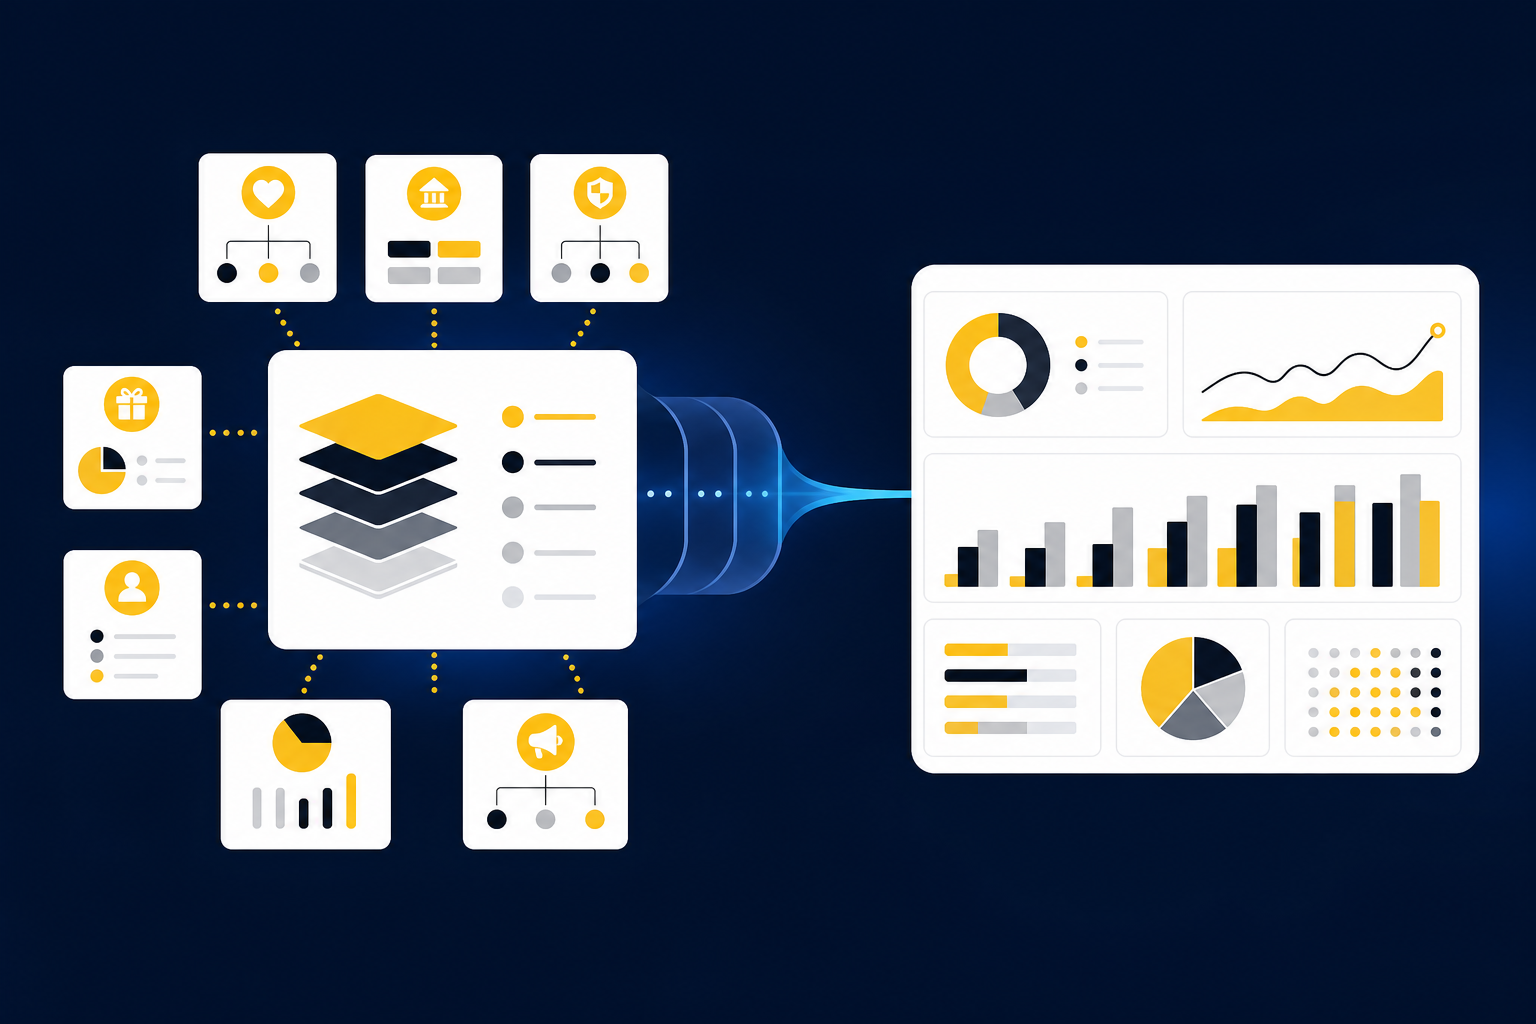
Begin by separating three questions. First, can the ledger represent the accounting structure your organization needs? Second, can the team produce the reporting, consolidations, and audit support expected from that structure? Third, how much work still happens in exports and spreadsheets before anything is ready for the ledger? A platform can pass the first two tests and still leave the close heavily manual.
The distinction matters because replacing the GL is a much larger decision than improving preparation. If your current system already holds accepted books, the better investment may sit between source systems and the ledger. If the chart, entity model, or reporting structure no longer represents the organization, an ERP evaluation is appropriate. Those are different problems.
Your first proof should be a recurring workflow with known inputs and a prior approved result. Ask each vendor or implementation partner to reproduce that result, preserve its dimensions, explain every exception, and show the reviewer controls before discussing expansion. To evaluate preparation separately, you can See Truewind in action against that same workflow. The comparison becomes concrete once everyone is working from the same source package and expected output.
An evidence-led comparison matrix
A useful matrix should not award checkmarks because a capability appears in a sales deck. It should record whether the capability is native, configured inside the ledger, delivered by a partner, or handled by a separate workflow layer. It should also name the evidence your team reviewed. A live walkthrough using your own accounting structure carries more weight than a generic feature label.
The matrix below treats QuickBooks Online, Sage Intacct, and NetSuite as candidate cloud nonprofit accounting systems of record. It does not assume that a requirement is native or available in every edition or configuration. Each cell tells you what the product has to prove for that requirement.
| Evaluation area | QuickBooks Online | Sage Intacct | NetSuite | Evidence to collect |
|---|---|---|---|---|
| Fund and restriction tracking | Keep it on the shortlist if your configured books preserve the required restrictions through entry, review, and reporting. | Require a configured walkthrough showing how fund and restriction dimensions survive the full workflow. | Require the same proof across the organization’s planned entity and reporting structure. | Source transaction, coded entry, reviewer view, and final report. |
| Grant accounting | Test one grant from award setup through activity review and closeout. | Test grant activity alongside the dimensions and reporting conventions your team already uses. | Test the grant inside the wider entity and consolidation model under consideration. | Grant agreement, activity schedule, indirect allocation, and reporting output. |
| Dimensions | Confirm the configured ledger can represent the combinations your reporting actually requires. | Ask the team to reproduce your current dimensional coding and exception process. | Ask how the proposed design preserves dimensions across entities and reporting layers. | Configuration map and a transaction with a split allocation. |
| Multi-entity operations | Test separation, due-to and due-from activity, review ownership, and entity reporting. | Test the same workflow across the entities expected to use the system. | Make entity structure part of the core design review rather than a later reporting question. | Entity diagram, intercompany example, and reviewer permissions. |
| Consolidations | Require the configured system and process to reproduce an accepted consolidated report. | Show how entity dimensions and adjustments reach the consolidated output. | Test the planned consolidation structure using representative entity activity. | Prior approved consolidation and current-period reproduction. |
| Reporting | Rebuild the board, grant, and management reports the team already depends on. | Require reports that preserve the dimensions used during preparation and review. | Require the proposed reporting model to reproduce the same accepted outputs. | Full report package with drill-down to supporting entries. |
| Audit trail | Trace one reported balance back through approval, entry, workpaper, and source. | Inspect the same path, including reviewer actions and dimensional coding. | Test traceability across entity adjustments and consolidated reporting. | Source file, workpaper, approval history, and posted record. |
| Ecosystem | List every dependency outside the ledger and identify who owns it. | Separate native ledger functions from implementation and workflow-layer responsibilities. | Map the full operating model, including any partner-delivered process. | Responsibility map with system owner and support owner. |
| Implementation burden | Compare the proposed design with the internal capacity available to configure and validate it. | Price and plan the accounting design, migration, testing, and reviewer training. | Evaluate implementation scope against the organization’s broader ERP change. | Written scope, assumptions, dependencies, and acceptance criteria. |
| Scalability | Model the next stage of entity, grant, transaction, and reviewer complexity. | Test whether the proposed configuration can preserve controls as that complexity grows. | Test the planned operating model rather than relying on a general scalability claim. | Future-state scenario and documented configuration response. |
| Pricing transparency | Record every quoted cost and the assumptions behind it. | Separate software, implementation, support, and workflow-layer costs in the evaluation. | Apply the same cost structure so proposals can be compared on equal terms. | Dated written quote with inclusions, exclusions, and renewal terms. |
Pricing deserves particular discipline. The absence of a figure in an article does not mean a vendor lacks published pricing, and a published starting point does not establish the cost of your configuration. Compare dated proposals built around the same entities, users, implementation scope, and support requirements. Otherwise, the lowest visible number may describe a different system than the one your nonprofit needs.
Separate native capability from configured process
A feature can appear in four different places: inside the ledger, in a configured workflow, through an implementation partner, or in a preparation layer that feeds the ledger. Buyers often collapse those into one checkmark. The result is a comparison that looks complete but does not explain who prepares the work, where the supporting evidence lives, or what happens when an item does not fit the standard rule.
Ask the same questions for every capability. Where is the rule maintained? Which source supports the calculation? Can the reviewer see what changed from the prior period? Does an exception stop before posting? Who owns corrections, and will that decision carry into the next period? Those questions expose the operating model behind the feature label.
A native capability is not automatically the better answer. Configuration may fit the organization more closely, while a workflow layer may handle preparation without forcing a ledger replacement. The tradeoff is ownership: your team needs to know which system controls the rule, which vendor supports it, and where approval occurs. For the preparation-layer evaluation, you can Book a Truewind demo around a recurring reconciliation your team already reviews.
Best-fit scenarios and their tradeoffs
QuickBooks Online may fit when continuity matters most. If the current QBO environment already produces accepted fund, grant, management, and audit outputs, replacing it may solve the wrong problem. The tradeoff appears when more preparation moves outside the ledger and reviewers have to reconstruct dimensions or support from separate files. Test that boundary directly before assuming the GL is the constraint.
Sage Intacct may fit when the evaluation centers on dimensions and structured accounting workflows. The buyer still needs to prove the configured fund, grant, multi-entity, reporting, and review process with its own data. Implementation is part of the accounting design, not an administrative step after selection. For a closer look at preparation around that ledger, Truewind’s Sage Intacct reconciliation workflow shows how reconciliation can remain tied to source and reviewer control.
NetSuite may fit when the organization is making a broader ERP decision around entity structure and consolidation. That broader scope also changes the evaluation burden. Finance should test the nonprofit accounting workflow inside the proposed operating model rather than assume an enterprise category label answers the fund, grant, or audit-trail questions. A larger platform decision still has to pass the same transaction-level proof.
Where an AI accounting execution layer fits
The ledger records the approved result. An execution layer prepares the work that has to happen first: combining donor and processor files, applying established mappings, preserving dimensions, checking totals, preparing the reconciliation, and surfacing exceptions for review. Sage Intacct or QuickBooks Online remains the system of record, while the preparation layer handles recurring work upstream.
Truewind fills that upstream role. It ingests donor-platform exports, processor reports, bank activity, prior workpapers, and other supported source files, then structures them for coding, reconciliation, and workpaper preparation. Historical treatment and reviewer corrections inform later periods. Missing statements, unexpected balance changes, and inconsistent classifications are routed back to the accountant rather than resolved without review.
The workpaper is the control surface. A reviewer can inspect the source, calculation, accounting treatment, exceptions, and sign-off before the output reaches the GL. Truewind documents connections for Sage Intacct and QuickBooks Online; native push is limited to those documented targets and requires reviewer confirmation. NetSuite is not a documented native push target in the supplied product scope.
Controlled adoption matters as much as capability. Start with one recurring workflow that has stable inputs and a known answer, compare the prepared output with the approved prior result, and capture reviewer corrections before expanding. In one documented customer example, an accounting firm reported reducing credit-card transaction categorization time by approximately 75 percent. That result is an example from one customer, not a nonprofit benchmark or a promised outcome.
The fit is narrower than autonomous accounting. Truewind does not replace the GL, decide accounting policy, or post without an accountant’s approval. For that evaluation, you can Get a Truewind demo using a workflow your team already understands. The reviewer remains responsible for the result.
A decision checklist for nonprofit finance teams
Before choosing nonprofit accounting software, require each shortlisted system to answer the same questions:
- Can it reproduce an accepted fund, grant, and management reporting package?
- Can the reviewer trace a reported balance back to source?
- Are dimensions preserved from preparation through posting and reporting?
- How are restrictions, split allocations, and timing differences reviewed?
- What happens when a statement is missing or a classification changes?
- Which capabilities are native, configured, partner-delivered, or handled upstream?
- Who owns implementation, rule changes, support, and reviewer training?
- What remains in spreadsheets after the proposed system is live?
- Does the dated proposal include every required system and service?
- Can the team test one recurring workflow before committing to broader scope?
Frequently asked questions
Which nonprofit accounting software is the right choice?
There is no universal winner. The right choice depends on fund and grant complexity, dimensions, entity structure, consolidation needs, reporting expectations, and the team’s implementation capacity. A product should earn its place by reproducing your required workflow and accepted output.
Should a nonprofit replace QuickBooks Online as it grows?
Growth alone does not answer the question. Replacement becomes relevant when the current accounting model cannot represent or report the organization’s required structure, even after reasonable configuration and process changes. If the books are sound but preparation remains manual, an upstream execution layer may address the harder problem without changing the GL.
Is Sage Intacct enough to automate the close?
A system of record does not remove every preparation step around it. Donor exports, processor settlements, bank activity, allocation rules, and workpapers still need to be combined and reviewed before posting. Evaluate the ledger and the upstream accounting process separately.
Can Truewind replace Sage Intacct, QuickBooks Online, or NetSuite?
No. Truewind is a preparation layer, not a general ledger or ERP. It prepares supported workpapers, reconciliations, schedules, and journal-entry drafts for accountant review, with documented native push limited to Sage Intacct and QuickBooks Online.
Choose the ledger, then test the work around it
A nonprofit should choose its system of record based on the accounting structure it has to preserve and the reporting it has to produce. Then it should examine everything that still happens before the approved entry reaches that system. The strongest evaluation follows one recurring workflow from source file to reviewer sign-off and makes every dependency visible. That is where platform fit becomes clear.
Turn this into a close-ready workpaper
Start with sample files or upload your own statements to see how Truewind prepares review-ready workpapers and journal entries.