A reviewer has a donor-platform export, a processor settlement report, and a bank deposit open on the same screen. The totals agree, but every line in the workpaper carries the same review status. Nothing tells the reviewer which items followed the approved process, which items changed, or whether an expected source never arrived. They check the full population because the workpaper gives them no defensible place to stop.
That pattern gets called exception review. It is usually full-population review with a few anomalies highlighted. The team still spends reviewer time proving that ordinary items are ordinary, while the missing statement or changed restriction treatment competes for attention in the same file.
Designing an exception-based review process starts somewhere less glamorous than anomaly detection. You first have to define what should not require line-by-line re-review. Those are the prepared-good items: work that followed the accounting team’s approved process. The workpaper has to prove that each item met that definition, separate anything that did not, and route those exceptions to the accountant who owns the judgment.
More alerts do not create an exception-based process
An anomaly flag identifies something unusual. An exception-based process decides what can proceed under the established treatment, what requires follow-up, and who has authority to resolve it. Those are different jobs. A workpaper can contain dozens of alerts and still force the reviewer to inspect every underlying line.
The control problem sits in the baseline. If the team has not documented which source should arrive, how totals should tie, which mappings apply, and what dimensional treatment is expected, the system has no stable definition of normal. It can point to statistical differences, but the reviewer still has to reconstruct the accounting process before deciding whether any difference matters.
Nonprofit accounting makes the distinction easy to see. A donation reconciliation may combine donor-platform activity, processor settlements, bank deposits, fees, refunds, fund restrictions, and program coding. A large deposit may be completely expected. A missing monthly export may matter far more, even though there is no transaction available to trigger a flashy alert.
The workpaper therefore needs to evaluate both activity and absence. It should show whether expected support arrived, whether the sources reconcile under the approved treatment, whether dimensions followed established rules, and whether anything changed from the prior period. Only then can the reviewer rely on the separation between prepared-good work and items needing judgment.
Seeing that separation in a live workflow matters because the review surface, not the alert count, determines whether routine items stay out of the follow-up queue. You can See Truewind in action to inspect how source-linked preparation and exception handoff fit together before anything reaches the GL.
Define prepared-good before defining exceptions
A useful exception policy begins with a strict description of what does not need to be re-performed line by line. “No anomaly detected” is not enough. The prepared item needs evidence that it followed the accounting team’s approved process and landed in the expected workpaper structure.
For a recurring reconciliation, that definition may require all of the following:
- The expected current-period source files are present.
- Source totals tie through the reconciliation under the approved treatment.
- Account mappings and dimensions match the team’s existing rules.
- Timing differences and reconciling items are visible rather than forced to zero.
- The workpaper contains the source, calculation, treatment, and reviewer status.
- No policy-sensitive change has been applied without accountant review.
The exact criteria will vary by workflow. A prepaid schedule does not have the same baseline as a donation reconciliation, and a brokerage rollforward does not have the same baseline as processor settlement coding. The point is not to impose a generic checklist. The point is to make the known process explicit enough that the workpaper can show when it was followed.
Prepared-good also does not mean approved without a person. It means the preparation matched the established process and does not require the reviewer to recheck every underlying step. The accountant still owns sign-off, materiality, accounting treatment, and any decision to post.
That distinction protects reviewer capacity without weakening accountability. A reviewer can confirm that the prepared population met the approved rules, then spend detailed attention on missing support, changed treatment, and items outside the known pattern. Full-population touching stops being the evidence of control. The workpaper becomes the evidence.
Missing expected events belong at the top of the queue
Accounting review often starts with what happened. A stronger process also asks what should have happened but did not. Missing statements, absent exports, skipped recurring entries, and incomplete support can be more consequential than an unusual transaction that still ties to source.
A donor platform illustrates the issue. If current-period activity is lower than the prior period, the change may be valid. If the export covers only part of the period, the lower total has a different meaning. The reviewer should not have to discover the missing coverage after opening individual transactions and comparing dates by hand.
Expected events need to be part of workflow design. The prior workpaper, close calendar, recurring source list, and established accounting process tell the team what should arrive and what preparation should occur. When an expected input is absent, the workpaper should not present the remaining population as complete.
The same principle applies across accounting workflows. A custodian statement that did not arrive, a recurring schedule that was not rolled forward, or an expected reconciliation that lacks one source is not merely an incomplete task. It changes what the reviewer can conclude from the prepared output.
Exception severity should reflect that difference. An item with complete support but unfamiliar coding may need classification review. A workpaper missing an expected source may need to remain blocked because the reviewer cannot establish completeness. Treating both as generic alerts hides the control distinction the accountant needs.
Design the workpaper around two visible populations
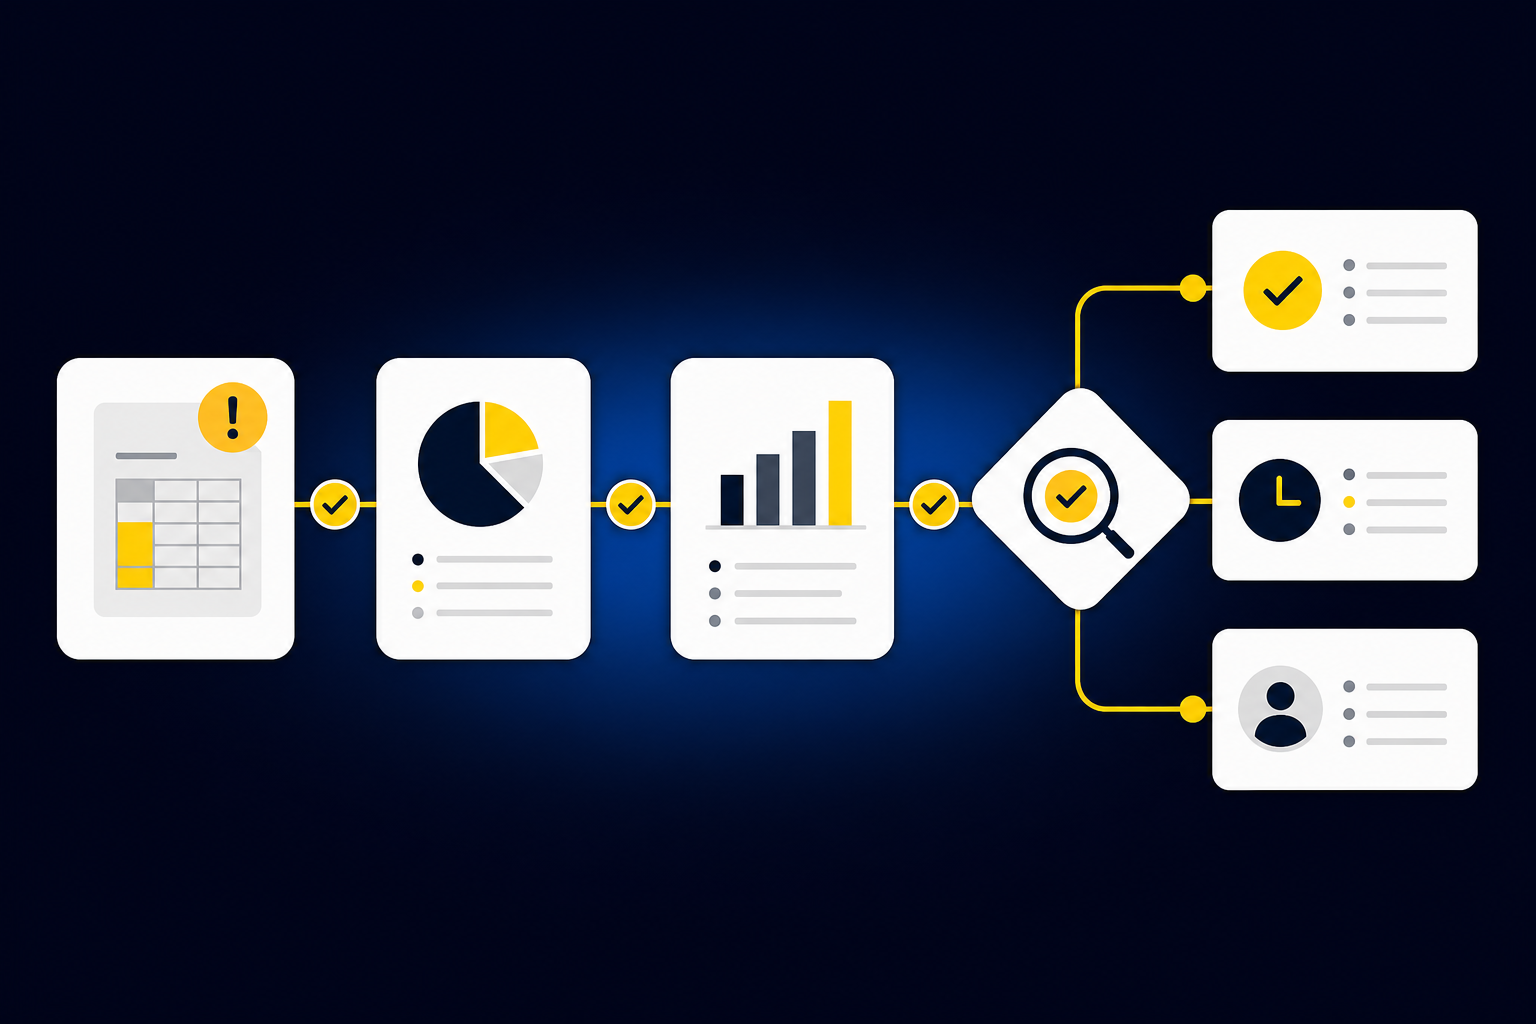
The workpaper should make the review decision visible before the reviewer opens the supporting detail. At minimum, it needs one population that followed the defined process and another that requires follow-up. Items blocked by missing support can be separated further when that status affects whether the workpaper is ready for sign-off.
Each prepared-good item should still be traceable. The reviewer needs to see which source produced it, how the calculation was performed, which mapping or allocation rule applied, and whether the treatment changed. Exception-based review reduces repetitive re-performance. It does not remove the evidence that would allow the reviewer to re-perform a step when needed.
The follow-up population needs more than an alert label. A useful exception includes the source context, the expected treatment, what differed, and the decision the accountant must make. “Unusual transaction” sends the reviewer back to the beginning. “Current classification differs from the approved prior-period treatment” gives the reviewer a place to start.
Reviewer notes also belong against the workflow, not in an email or a separate copy of the spreadsheet. If a classification is corrected, the next preparer should be able to see the approved decision. If the reviewer makes a one-period exception, the workflow should not convert that decision into a permanent policy without explicit approval.
A live review is useful here because static screenshots rarely show how source evidence, exceptions, and reviewer actions stay connected. You can Book a Truewind demo to walk through the point where prepared work separates from items requiring accountant judgment.
Route ownership according to the judgment required
Not every exception belongs with the controller. Some follow-up items involve missing files or incomplete preparation that a preparer can resolve. Others involve cutoffs, classification, allocation, or accounting policy and need a reviewer with the authority to make that call.
The names of the roles will vary, but the routing principle should stay consistent. Ownership follows the judgment required and the effect of the decision. A source-format problem should not wait in the same queue as a changed restriction treatment, and a new accounting-policy decision should not be handled as if it were routine coding cleanup.
Materiality belongs inside that routing logic, using thresholds the accounting team already owns. The system should not invent materiality or decide that an unfamiliar item is immaterial because its amount appears small. Context matters. A low-dollar item can still expose a repeated classification problem, an incomplete source, or a policy change.
Clear ownership also prevents exception queues from becoming another full-population review. If every flag lands with the same reviewer, the queue grows without distinguishing preparation issues from judgment issues. The reviewer then spends time triaging work that could have been resolved earlier in the workflow.
The control is not the existence of a queue. The control is that each exception shows why it was routed, which evidence supports it, who can resolve it, and whether the workpaper can proceed before that resolution.
Capture corrections without changing policy by accident
A correction should improve the next period when it reflects an approved recurring treatment. If a reviewer confirms that a processor fee maps to a particular account and dimension under the team’s established rules, the next preparation can apply that history. Requiring the reviewer to make the same correction every month is not added control.
Policy changes are different. A new cutoff rule, allocation method, or classification treatment should remain explicit because it changes how future work will be prepared. Historical learning cannot become a back door for changing accounting policy.
The review workflow therefore needs to preserve two pieces of context: what the reviewer changed and why the change should or should not carry forward. A recurring correction can become part of the preparation logic after approval. A one-time decision should remain tied to that period unless the accountant deliberately updates the rule.
That record matters when the next exception appears. The reviewer can compare the current item with prior approved treatment instead of relying on memory or searching through email. The workflow becomes more consistent without pretending that every new item is the same as the last one.
One Truewind customer story shows the capacity available when routine categorization follows approved treatment. An accounting firm reduced credit-card transaction categorization time by approximately 75 percent. That result belongs to one customer, not a general benchmark, but the mechanism is relevant: recurring treatment moved into preparation while people remained responsible for review and client work.
Truewind prepares the work upstream of the ledger
Truewind sits between recurring source files and Sage Intacct or QuickBooks Online. The GL remains the system of record. Truewind structures the inputs, applies the accounting team’s historical treatment, and prepares workpapers, reconciliations, schedules, and journal-entry drafts for accountant review.
For a multi-source reconciliation, Truewind can align donor-platform activity, processor reports, and bank activity using the team’s prior treatment. Fees, refunds, and timing differences remain visible in the supporting schedule. Unreconciled items are surfaced with source context rather than forced into agreement.
The review workflow keeps prepared output beside its exceptions and underlying sources. Accountants can confirm an item, adjust it, or send it back for preparation. Reviewer decisions are captured for later periods, but novel items and policy changes still return to the accountant.
Workpaper rollforward uses the prior workpaper, current-period sources, and ERP balances to prepare the new period in a familiar format. Balances and supporting schedules update, required journal-entry drafts are prepared with source-linked support, and exceptions remain visible for handoff. Truewind does not invent accounting policy or resolve those exceptions on its own.
After reviewer sign-off, approved structured output can be pushed to Sage Intacct or QuickBooks Online with coding and dimensions preserved. Nothing posts without accountant confirmation. Teams looking for autonomous posting or a replacement GL are evaluating a different kind of product.
If your team wants to test that preparation and review boundary against a real recurring workpaper, you can Get a Truewind demo and bring the workflow, prior approved result, and source files you already use.
Start with one workflow the reviewer already understands
Exception-based review should be adopted through controlled iteration, not a broad switch from manual review to autonomous accounting. Start with a recurring workflow that has known inputs, a prior approved workpaper, established treatment, and a reviewer who can explain the expected result.
Run the preparation against that known answer. Compare the source coverage, calculations, mappings, dimensions, and exception handling. Capture corrections, then repeat the workflow until the team can see that prepared-good items are consistently separated from items requiring judgment.
Expansion should follow evidence from that process. A successful donation reconciliation does not prove that every accrual schedule or entity-level rollforward is ready for the same treatment. Each workflow needs its own expected sources, accounting rules, review conventions, and exception ownership.
The target is not a close where the accountant sees nothing. It is a workpaper process where the accountant sees what matters: material exceptions, missing expected events, and policy-sensitive changes. Routine preparation stays traceable, the GL remains the system of record, and reviewer attention moves to the decisions only a reviewer should make.
Frequently Asked Questions
How do I design an exception-based review process?
Start by clearly defining what items do not need a line-by-line review. Identify prepared-good items that followed the approved accounting process. Ensure your workpaper shows evidence of this compliance, such as the presence of expected source files and matching totals. Then, separate any exceptions that require further judgment and route them to the appropriate accountant. This way, you can efficiently focus on items that truly need attention.
What if I encounter missing expected events in my review?
If you notice missing expected events, prioritize these items in your review process. For example, if a donor platform export is absent, this could significantly impact your conclusions. Make sure your workpaper reflects this incompleteness, and don't present the remaining items as complete. Instead, highlight these gaps so they can be addressed before moving forward.
Can I use Truewind to streamline my month-end close?
Yes, you can use Truewind to help prepare your workpapers and reconciliations. It organizes your source documents and applies your accounting team's historical treatment to create a structured workflow. This reduces the repetitive work involved in preparing for the month-end close, allowing you to focus on exceptions and items that require judgment.
When should I separate prepared-good items from exceptions?
You should separate prepared-good items from exceptions as soon as you have established the criteria for what constitutes prepared-good work. This typically involves confirming that all expected source files are present and that totals reconcile under the approved treatment. Once identified, you can route exceptions to the appropriate accountant for further review, ensuring a more efficient process.
Why does my review process need to focus on expected events?
Focusing on expected events is crucial because missing items can have significant implications for your financial reporting. For instance, if a recurring entry is skipped or a statement is not received, it can lead to incorrect conclusions about your financial position. By designing your review process to highlight these missing elements, you ensure that the workpaper reflects the true state of your accounts.
Turn this into a close-ready workpaper
Start with sample files or upload your own statements to see how Truewind prepares review-ready workpapers and journal entries.